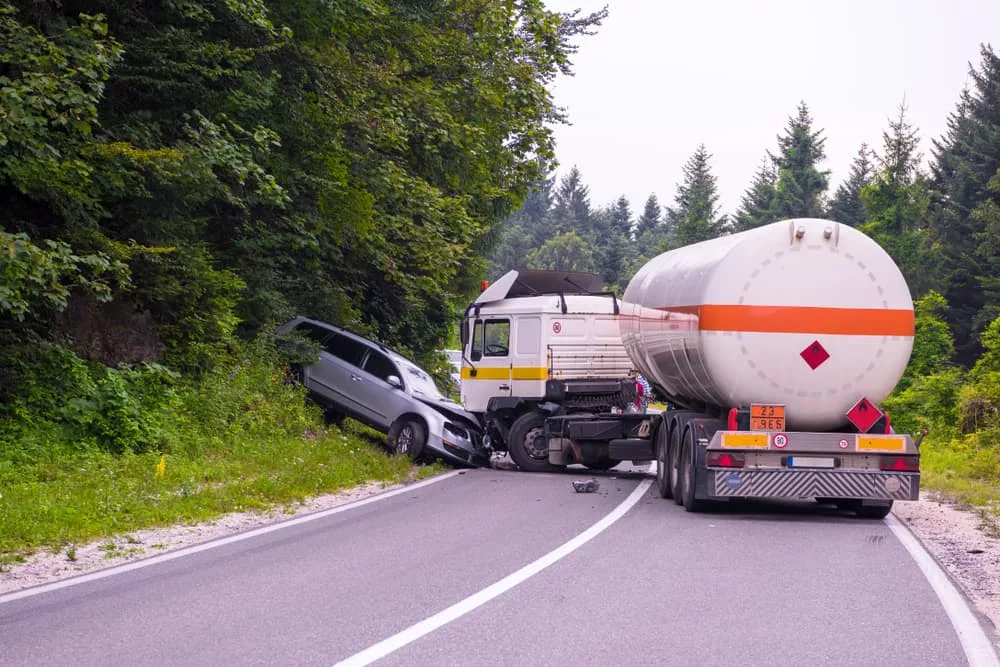

Suffering injuries in a car accident is always a painful and frustrating experience. At best, they are a significant inconvenience, eating up time you did not have to spare. Yet the consequences of many traffic collisions are far worse. A bad crash can turn your life upside down in an instant. Finding out the person who caused the accident does not have auto insurance can make a terrible situation into one that feels impossibly overwhelming. Reach out to a car accident lawyer.
How will you afford your bills? What options do you have when the at-fault driver has no insurance, or has a policy too small to cover what happened to you? Florida handles these claims through a specific sequence of coverages, and the order matters. Below, we explain how that sequence works, where uninsured and underinsured motorist (UM) coverage fits, and the notice rule that protects your UM claim if the other driver’s insurer offers its policy limits.
Car Insurance Laws in Florida
Like nearly every state, Florida requires motorists to carry auto insurance. As a minimum, all motorists in the state must purchase:
- $10,000 in personal injury protection (PIP) coverage: PIP pays 80 percent of reasonable, medically necessary expenses and 60 percent of lost gross income, regardless of who caused the crash. You must receive initial treatment within 14 days of the accident, and the full $10,000 medical benefit applies only if a qualifying provider determines you had an emergency medical condition. Otherwise, medical benefits are limited to $2,500.
- $10,000 in property damage liability (PDL) coverage: PDL pays for damage your vehicle causes to someone else’s property in a crash, as required by section 324.022, Florida Statutes.
Florida’s No-Fault Car Accident Law
Because Florida is a no-fault car accident state, any driver involved in a traffic collision must file a claim with their own insurance provider first. However, many accident-related injuries require extensive treatment that can cost tens of thousands of dollars or more. Because PIP coverage will only reimburse you for a small portion of these expenses, you will need to look to other sources of compensation if your injuries are severe.
If you have uninsured motorist coverage, you can file a claim under your own policy for losses beyond PIP. In Florida, insurers must offer this coverage, and it applies unless a named insured rejected it, or selected lower limits, in writing on a state-approved form. Florida treats an “underinsured” driver as a type of uninsured driver, so the same UM coverage usually answers both situations. If you do not have UM coverage, you may need to pursue the at-fault driver, and anyone else who shares responsibility, directly. Our guide to filing a UM/UIM claim with a lawyer covers the claim process itself.
Uninsured and Underinsured Drivers in Florida
According to the Insurance Information Institute, which reports Insurance Research Council estimates, about 20.6 percent of Florida motorists were uninsured in 2023, compared with a national rate of 15.4 percent. That placed Florida seventh among the states, which means roughly one in five drivers you share the road with may carry no liability coverage at all.
However, you may face trouble even if the at-fault driver has the minimum legal coverage. Florida does not mandate bodily injury (BI) liability insurance. As such, even drivers who have the minimum legal coverage may lack sufficient insurance to compensate those they injure. If you suffer injuries in an accident and your PIP coverage does not fully cover the expenses, a driver with minimum coverage will not have a policy that can compensate you for the remainder of your losses.
In these situations, the question becomes which other sources of payment may be available, starting with your own policy.
How Florida Defines an Underinsured Driver
Under section 627.727, Florida Statutes, a vehicle counts as “uninsured” for UM purposes not only when it has no coverage, but also when its bodily injury liability limits are less than the total damages the injured person suffered. In other words, a driver can carry a valid policy and still be underinsured for your claim. Florida UM coverage is also written to sit on top of, without duplicating, benefits such as PIP and workers’ compensation.
The Order in Which Coverage Usually Pays
Every claim is different, but after a crash with an underinsured driver in Florida, payment often comes from these sources in roughly this order:
- Your PIP coverage for a share of medical bills and lost income, up to its limit
- The at-fault driver’s bodily injury liability policy, if they carry one and your injury meets Florida’s permanent injury threshold for pain and suffering
- Your own UM coverage for losses that exceed the at-fault driver’s limits, up to your UM limits
- Other responsible parties, such as an employer or a vehicle owner who loaned the car
- The at-fault driver personally, through a judgment, which may be difficult to collect
If the at-fault driver was using someone else’s car with permission, section 324.021 can make a natural-person owner liable up to $100,000 per person and $300,000 per incident for bodily injury, plus up to an additional $500,000 in economic damages when the driver had less than $500,000 in coverage. That provision can matter a great deal when the driver’s own policy is small. Our article on what happens when a car accident exceeds insurance limits looks at larger losses in more detail.
Notify Your UM Insurer Before Accepting the Other Driver’s Policy Limits
One of the most important steps in an underinsured claim happens when the at-fault driver’s insurer offers its full policy limits. Section 627.727(6) says that if you intend to settle with the liability insurer and release the at-fault driver, written notice of the proposed settlement must be sent by certified or registered mail to every underinsured motorist insurer that covers you.
Your UM insurer then has 30 days after receiving the notice to either approve the settlement or, if it wants to keep its right to pursue the at-fault driver, pay you the amount of the liability insurer’s written offer within that 30-day window. Skipping this step or signing a release too early can put your UM claim at risk, so ask a lawyer to review any limits offer before you accept it.
Stacked and Non-Stacked UM Policies
Florida policies can be written as “stacked,” which may let you combine UM limits for more than one vehicle on your policy, or “non-stacked,” which generally limits you to the coverage on one vehicle in exchange for a lower premium. Your declarations page shows which you have, and a lawyer can review the policy with you if you are unsure.
Factors Determining Liability

To be eligible to file a lawsuit against the other driver, you must first establish that your injuries meet the severity threshold established by the state’s tort exemption. Next, you must show that the other driver’s negligence led to your accident-related injuries and losses.
A car accident lawyer can help you gather the medical evidence needed to show that your injuries meet this threshold, and investigate how the crash happened to show that the other driver was negligent. The same proof supports a UM claim, because your UM insurer generally pays what you could have recovered from the at-fault driver.
Negligence is a legal term that means failing to exercise the necessary care a given situation warrants. In the context of driving a car, that could mean speeding, failing to check blindspots before merging, or running a red light. Here are some other common examples of negligent behavior on the road:
Drunk Driving (DUI)
A blood alcohol content (BAC) of 0.08 or higher is illegal for anyone who gets behind the wheel in Florida. Not only may they face criminal charges, but you could hold them accountable for your accident-related losses.
Distracted Driving
Driver distraction is among the most common causes of accidents on Florida’s roads and highways. Although Florida law prohibits drivers from texting behind the wheel, people frequently get into accidents because of illicit cell phone use. Other examples of driver distractions include eating, operating a GPS device, and reaching into the back seat for a lost item. If an investigation determines that a driver’s distraction led to your injuries, you can sue them for negligence.
Reckless Driving
At the criminal level, Florida law defines reckless driving as the operation of a vehicle “in willful or wanton disregard for the safety of persons or property.” In addition to the criminal charges the reckless driver will likely face, you could file a lawsuit against them, seeking compensation for the harm they caused you. You could also request punitive damages, which punish the driver financially for their egregious behavior.
How Shared Fault Affects Your Recovery
Florida uses a modified comparative fault rule for most negligence claims. Under section 768.81(6), a person found more than 50 percent at fault for their own harm may not recover damages, and a person found 50 percent or less at fault has their award reduced by their share of fault. Insurers on both sides, including your own UM carrier, may raise this issue, so early evidence about how the crash happened matters.
When the At-Fault Driver Cannot Cover Your Losses
Some uninsured and underinsured drivers lack coverage because a policy lapsed, and others carry only the minimum required coverage because of cost. Either way, you can still bring a claim against the driver if their negligence caused your injuries, but the practical question is whether a judgment could be collected.
A Miami car accident attorney can help you weigh that question before you spend time and money on a lawsuit. A court judgment can be enforced against a person’s non-exempt assets, but Florida law protects certain property, such as a qualifying homestead, from most creditors. For that reason, your own UM coverage and any other responsible parties are often the more reliable sources of payment.
The other driver might not be the only party responsible. An employer may be liable if the crash happened while the driver was working, the owner of a borrowed vehicle may share liability as described above, and a manufacturer may be responsible if a defective part contributed to the crash.
Compensation You Can Claim after a Car Accident in Florida
When you file an accident claim or lawsuit against a negligent driver in Florida, you can demand compensation for a wider range of losses than you could obtain via your PIP coverage alone. While your own insurance may only cover 80 percent of your injury expenses and 60 percent of lost earnings (up to $10,000), a successful claim or suit against the at-fault driver can allow you to recover the full extent of your losses.
Your compensation may include:
- Medical bills
- Lost earnings due to missed time at work
- Property damage
- Rehabilitation, including physical and occupational therapy
- Mental health therapy
- Reduced income capacity due to disability or disfigurement
In addition to these economic losses, a successful lawsuit can provide you with compensation for non-economic damages, including:
- Physical and psychological pain and suffering
- Scarring and disfigurement
- Disability and permanent impairment
- Loss of enjoyment of life
In limited circumstances involving intentional misconduct or gross negligence, Florida law may also allow a claim for punitive damages, which are meant to punish rather than compensate. These claims require court approval and are not available in most car accident cases.
Working out which damages apply and what they are worth can be complicated, especially when several policies with different limits are involved. A Florida car accident attorney can help you identify each coverage that may apply and pursue fair compensation from each.
How a Florida Auto Accident Attorney Can Help You
Florida’s insurance rules can create real complications when the at-fault driver has little or no coverage. A lawyer can help you identify every coverage that may apply, meet the notice requirements in your policy and in Florida law, and avoid steps that could reduce your UM claim.
They can help you by:
- Ascertaining whether you have grounds for an insurance claim or lawsuit
- Investigating the circumstances and causes of the accident
- Determining which party or parties were liable for your injuries
- Examining police reports
- Gathering necessary documents to present to the insurance companies, such as your medical records and employment information
- Negotiating with each insurance adjuster for fair compensation, and sending the required notice to your UM insurer before any limits settlement
- Filing a lawsuit against anyone who bears liability if insurance will not cover your losses
Deadline for Filing a Car Accident Lawsuit in Florida
For most negligence claims arising after March 24, 2023, section 95.11, Florida Statutes, allows two years to file a lawsuit, down from the four years that applied to earlier claims. A claim under your own UM policy may follow a different deadline, and your policy can impose its own notice requirements. The PIP 14-day treatment rule also applies. Because evidence and witness memories fade, it is wise to speak with an attorney about all of these deadlines as soon as possible.
Steps to Take After a Collision with an Uninsured Driver
Before filing legal action, you should take the following steps to protect yourself and optimize your chances of recovering the compensation you deserve.
Seek Medical Attention
Ideally, anyone who has been in an accident should seek immediate medical attention. Even if you do not believe you have suffered any harm in the crash, a doctor’s examination can discover injuries that might otherwise remain invisible for several days or longer. The adrenaline rush from being in a traffic collision can mask the pain you might otherwise feel.
If you wait more than 14 days to receive initial treatment, you may lose access to PIP benefits. A long gap between the crash and your first visit can also give an insurer grounds to question whether the accident caused your injuries, so early treatment and consistent follow-up help protect both your health and your claim.
Review Your Insurance Policy
Many people are unsure what their policy covers. Look at your declarations page for uninsured motorist coverage, its limits, and whether it is stacked or non-stacked. Also check whether a household member’s policy may cover you, since some UM policies extend to relatives who live with the policyholder.
Speak to an Experienced Florida Car Accident Attorney
Many people who have been in an accident with an underinsured driver feel so perplexed about filing a claim that they put off taking action until it is too late. Others might believe that their circumstances make their chances of successfully recovering compensation so unlikely that they dismiss the possibility of a lawsuit out of hand.
Before you give up, speak with a car accident attorney about your situation. A lawyer familiar with Florida insurance law can explain options that may be broader than you assume, from UM coverage to owner liability, and handle the insurance paperwork while you focus on recovering.
The Bottom Line
Nobody should have to shoulder the financial burden of an accident they did not cause. If an underinsured driver injured you, our Miami car accident lawyers at Redemption Law can review your policies, explain how Florida’s UM rules apply, and talk with you about next steps during a free consultation. Reach out to a personal injury lawyer today.
Frequently Asked Questions About Underinsured Driver Claims
What is the difference between an uninsured and an underinsured driver in Florida?
An uninsured driver has no bodily injury liability coverage. An underinsured driver has some coverage, but limits lower than the total damages you suffered. Section 627.727 treats both as uninsured motor vehicles for purposes of your own UM coverage, so the same coverage usually applies to both situations.
Does Florida require drivers to carry bodily injury liability insurance?
Florida requires $10,000 in personal injury protection and $10,000 in property damage liability coverage. Bodily injury liability coverage is not part of that basic requirement for most drivers, which is one reason underinsured claims are common in Florida.
Can I accept the at-fault driver’s policy limits and still make a UM claim?
Often yes, but Florida law requires written notice of the proposed settlement to your underinsured motorist insurer by certified or registered mail. The insurer then has 30 days to approve the settlement or pay you the amount of the offer to preserve its own rights. Signing a release before following this process can put your UM claim at risk.
What if the driver who hit me was using someone else’s car?
Florida can hold the owner of a vehicle responsible when they let someone else drive it. For an owner who is a natural person, section 324.021 sets liability limits of $100,000 per person and $300,000 per incident for bodily injury, plus up to $500,000 more in economic damages if the driver had less than $500,000 in coverage.
How long do I have to file a claim after a crash with an underinsured driver?
For most negligence claims arising after March 24, 2023, Florida allows two years to file a lawsuit against the at-fault driver. Claims under your own UM policy can follow different deadlines and policy notice rules, and PIP requires treatment within 14 days, so it helps to speak with a lawyer early.
Christopher D. Alas is the founder and managing attorney of Redemption Law, a personal injury firm licensed in Texas and Florida. He oversees the firm’s litigation strategy and draws on a background in tax law to help clients understand the financial and legal implications of their injury claims. Read full bio
Christopher D. Alas is the founder and managing attorney of Redemption Law, a personal injury firm licensed in Texas and Florida. He oversees the firm’s litigation strategy and draws on a background in tax law to help clients understand the financial and legal implications of their injury claims. Read full bio
Related articles
Related articles Related articles Related articles Related articles Related articles Related articles Related articles Related articles Related articles Related articles
Car Accident
10 Aug 2026
How Texas’s 51 Percent Bar Rule Can Make or Break Your Car Accident Case
Car Accident
06 Jul 2026
What Happens if the Other Driver Leaves the Scene of an Accident in Texas?